For decades, industrial cybersecurity operated under a relatively simple assumption – operational technology (OT) networks were isolated, specialized, and therefore difficult for external attackers to reach. That assumption is rapidly becoming obsolete. Factories are adopting connected sensors, utilities are modernizing grids, energy companies are integrating remote monitoring, and industrial assets are increasingly communicating across IT and OT environments.
The consequence is a new strategic reality – the more connected industrial operations become, the more cybersecurity must become part of the infrastructure itself. OT firewalls are moving into this role by controlling industrial traffic, segmenting networks, restricting unauthorized access, and protecting systems that cannot afford unexpected downtime.
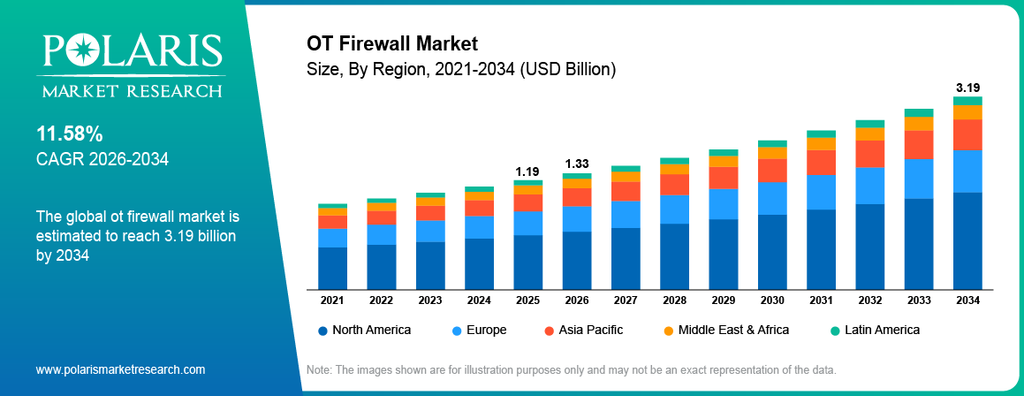
Polaris Market Research estimates that the global OT firewall market was valued at approximately USD1.19 billion in 2025 and is projected to reach USD3.19 billion by 2034, expanding at an 11.58% CAGR from 2026 to 2034. But the more significant business story is what is driving that growth – industrial digitalization is transforming cybersecurity from an IT expense into an operational resilience investment.
Why industrial digitalization is changing the firewall equation
Traditional enterprise cybersecurity can often tolerate disruption, patching windows, and frequent infrastructure changes. Industrial environments cannot always make those trade-offs. A manufacturing line, power station, pipeline, or water facility may depend on legacy control systems that must operate continuously. This makes OT security fundamentally different.
As industrial IoT, smart manufacturing, SCADA systems, and connected control environments expand, organizations need security mechanisms capable of understanding industrial protocols and protecting operational assets without interfering with production. Network segmentation has consequently become a strategic priority because it can limit lateral movement and isolate sensitive assets if an intrusion occurs.
Polaris identifies industrial network segmentation, critical-infrastructure protection, industrial IoT adoption, and smart manufacturing as important forces supporting market expansion.
For business leaders, this suggests a broader lesson – cybersecurity architecture must evolve at the same speed as industrial connectivity.
Security investment is becoming an uptime decision
An OT firewall is no longer simply a defensive technology purchased by an IT department. Its value increasingly connects to production continuity, operational safety, regulatory compliance, and business reputation.
This is particularly relevant for energy and utilities, which represented the largest end-use segment in 2025 with a 28.7% share. In critical infrastructure, a cybersecurity incident can have consequences far beyond compromised data – it can affect electricity supply, manufacturing output, transportation systems, or essential public services.
That changes how organizations should evaluate OT security investments. The question is not merely, ‘How much does the firewall cost?’ It is, ‘What is the financial and operational exposure if the industrial network is compromised?’
The next growth frontier: From on-premises control to cloud-managed security
The OT firewall market is also revealing an important transition in enterprise architecture. On-premises deployment led the market in 2025 because mission-critical industries continue to prioritize direct control over industrial networks and operational data.
Yet the fastest-growing deployment model is expected to be cloud-managed, with a projected 16.3% CAGR.
This contrast is strategically important. Industrial organizations are not necessarily abandoning on-premises security; instead, they are seeking centralized visibility, remote monitoring, policy management, and scalable security operations.
“For decades, industrial cybersecurity operated under a relatively simple assumption – operational technology (OT) networks were isolated, specialized, and therefore difficult for external attackers to reach. That assumption is rapidly becoming obsolete. Factories are adopting connected sensors, utilities are modernizing grids, energy companies are integrating remote monitoring, and industrial assets are increasingly communicating across IT and OT environments”
For vendors, the opportunity therefore extends beyond selling a hardware appliance. The competitive advantage will increasingly come from integrating firewalls with asset visibility, threat intelligence, anomaly detection, centralized management, and broader OT security platforms.
Regional insights: Where the strategic opportunity is emerging
North America remains the established security market
North America accounted for 39.8% of global OT firewall revenue in 2025, supported by significant investment in industrial cybersecurity and critical infrastructure protection.
The region’s opportunity is strengthened by mature industrial infrastructure and regulatory pressure. For vendors, North America represents a market where customers are increasingly sophisticated and expect security solutions to integrate with existing operational environments.
Asia Pacific offers the strongest expansion opportunity
Asia Pacific is projected to register the fastest growth, with a 14.8% CAGR during the forecast period. Rapid industrial automation, smart manufacturing, and digital infrastructure expansion are creating a large new installed base of connected industrial assets.
This makes the region strategically important not only for demand but also for long-term industrial cybersecurity ecosystems. Companies that establish relationships with manufacturers, automation providers, system integrators, and utilities could gain an advantage as OT security becomes embedded into new industrial projects.
Europe, meanwhile, benefits from cybersecurity regulation and industrial digitalization, while Latin America and the Middle East & Africa offer opportunities as critical infrastructure modernization accelerates.
Competitive landscape: The battle is moving beyond firewall performance
The OT firewall market remains moderately fragmented, with competition shaped by product performance, industrial protocol support, certifications, threat intelligence, and integration capabilities.
Major participants include Fortinet, Palo Alto Networks, Cisco, Check Point Software Technologies, Nozomi Networks, Siemens, Honeywell, Belden, Moxa, TXOne Networks, Waterfall Security Solutions, Schneider Electric, Rockwell Automation, Dragos, Armis, and others. The strategic battleground, however, is expanding.
Industrial customers increasingly need solutions that combine deep packet inspection, asset visibility, AI-based threat detection, secure remote access, segmentation, and centralized management. Polaris identifies AI-based threat detection, cloud-based management, zero-trust architecture, and continuous asset visibility as important technology developments shaping the market.
For vendors, this means differentiation will increasingly depend on how effectively cybersecurity tools fit into operational workflows rather than on firewall functionality alone.
The biggest barrier may be the industrial environment itself
Despite strong demand, OT firewall adoption is not frictionless. Legacy systems can require extensive customization, while deployment can be expensive and t
ime-consuming. Industrial organizations also face shortages of cybersecurity specialists and lengthy procurement cycles for critical infrastructure.
This creates an opportunity for vendors that can make security easier to deploy without disrupting operations.
The winners may therefore be companies that can translate sophisticated cybersecurity capabilities into simple operational outcomes – better visibility, fewer vulnerabilities, faster response, easier compliance, and minimal disruption to production.
Future outlook: OT security will become part of industrial design
The future of OT cybersecurity is moving from reactive protection toward embedded resilience. As factories, grids, transport systems, and other infrastructure become more connected, cybersecurity will increasingly need to be designed into industrial architecture from the beginning rather than added after deployment.
That creates a durable growth opportunity for OT firewall providers. Polaris projects the market to expand to USD 3.19 billion by 2034, reflecting the increasing importance of protecting connected industrial environments.
The strongest growth opportunities are likely to emerge where three trends intersect – industrial automation, regulatory pressure, and the expansion of connected assets.
Conclusion
The OT firewall market is growing because the industrial world is becoming connected – and connectivity changes the economics of cybersecurity.
The strategic opportunity is therefore larger than firewall deployment. OT security is becoming a mechanism for protecting uptime, operational continuity, critical infrastructure, and the value created by Industry 4.0 investments.
For industrial executives, the key question is no longer whether OT environments need stronger cybersecurity. It is whether security architecture can evolve quickly enough to protect the increasingly connected systems on which modern operations depend. For technology vendors and investors, that shift could make OT cybersecurity one of the most important infrastructure-security opportunities of the next decade.